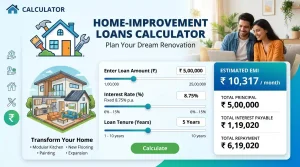
Home improvement loans with bad credit can help homeowners pay for repairs, renovations, and essential upgrades. Options may include personal loans, secured loans, FHA Title I loans, and local assistance programs. Approval depends on factors such as income, existing debt, credit history, and the lender’s requirements. Compare the total borrowing cost before applying.
Key Takeaways
- Bad credit does not automatically prevent approval. Some lenders consider income, employment, debt, and payment history alongside your credit score.
- Compare several financing options. Personal loans, secured loans, government-backed programs, and local grants may fit different needs.
- Check the full cost. Compare APRs, origination fees, repayment periods, and late-payment penalties.
- Protect your home. Secured loans can put your property at risk if you cannot repay the debt.
- Explore assistance before borrowing. Eligible homeowners may qualify for grants, repair programs, or other affordable options.
Home Improvement Loans With Bad Credit
If your credit score is low, finding affordable money for home repairs can feel difficult. A leaking roof, broken furnace, damaged plumbing, or outdated electrical system may need attention long before your credit improves.
The good news is that some lenders work with borrowers who have less-than-perfect credit. You may also qualify for a secured loan, a government-backed financing program, or local home repair assistance. However, eligibility and costs vary, so it pays to compare options before signing an agreement.
This guide explains how home improvement loans with bad credit work, which financing options to consider, and how to improve your chances of approval. You will also learn what fees to watch for, when borrowing against your home may be risky, and where to find assistance that could reduce the amount you need to borrow.
What Does “Home Improvement Loans With Bad Credit” Mean?
Home improvement loans with bad credit are financing options for homeowners whose credit histories make traditional borrowing more difficult. People generally use these loans to pay for repairs, renovations, replacements, or upgrades without covering the entire cost upfront.
A lender may consider your credit score, income, existing debts, employment, and payment history when reviewing your application. Some lenders accept lower scores, while others require stronger credit or additional security.
There is no single credit score that guarantees approval across all lenders. A lower score may mean a higher interest rate, a smaller loan, or stricter repayment terms.
Why Consider Different Home Improvement Financing Options?
Comparing several options can help you find financing that fits your project and budget. The first offer you receive may not be the most affordable.
Consider these benefits of shopping around:
- Lower borrowing costs: Another lender may offer a better APR or fewer fees.
- More approval opportunities: Different lenders use different eligibility standards.
- Flexible repayment: Some options offer fixed monthly payments or longer repayment periods.
- Reduced financial risk: Grants and assistance programs may help you avoid taking on unnecessary debt.
- Better project planning: Comparing loan amounts with actual repair estimates helps prevent overborrowing.
The right choice depends on how urgently you need repairs, how much you need, whether you own your home outright, and what monthly payment you can afford.
10 Best Financing Options for Home Improvement Loans With Bad Credit
These are ten financing routes worth exploring. They are not ten guaranteed loan approvals. Each has different costs, eligibility rules, and risks.
1. Personal Loans for Home Improvements
Meaning: A personal loan lets you borrow a lump sum and repay it in regular installments. Many personal loans are unsecured, meaning you do not pledge your home as collateral.
Best for: Homeowners who need a defined amount for repairs and want predictable monthly payments.
Example 1: You borrow $8,000 to replace damaged flooring and repair a bathroom.
Example 2: You use a fixed-rate loan to replace a failed water heater and repair leaking pipes.
Quick Tip: Look for lenders that offer prequalification with a soft credit check. Compare the APR, origination fee, loan term, and total repayment amount before applying.
2. Secured Personal Loans
Meaning: A secured personal loan requires collateral, such as an eligible vehicle or savings account. Depending on the lender and collateral, this security may improve your chances of approval or help you qualify for a lower rate.
Best for: Borrowers who have an eligible asset and understand the consequences of default.
Example 1: You use an eligible asset to secure financing for essential window replacements.
Example 2: You pledge a savings account as collateral for a smaller home repair loan.
Quick Tip: Ask exactly what the lender can seize if you miss payments. Never risk an essential asset unless you understand the repayment obligations.
3. FHA Title I Property Improvement Loans
Meaning: The Federal Housing Administration insures eligible property improvement loans made by approved private lenders. These loans can finance qualifying repairs and improvements, including certain projects involving manufactured homes. HUD does not lend the money directly.
HUD+1
Best for: Homeowners who need improvement financing and want to investigate a federal loan insurance program.
Example 1: You explore financing for repairs to an older home’s structural components.
Example 2: You contact an approved lender about funding eligible improvements to a manufactured home.
Quick Tip: Do not assume a low credit score qualifies you automatically. HUD’s program materials state that borrowers need a good credit history and the ability to repay, and each application remains subject to applicable requirements. Check the official HUD Title I information.
HUD+1
4. FHA 203(k) Rehabilitation Loans
Meaning: An FHA 203(k) loan combines eligible home purchase or refinancing costs with funds for qualifying rehabilitation work. It is a mortgage program, not a simple unsecured repair loan.
Best for: Eligible buyers purchasing a home that needs renovation and qualifying homeowners considering a mortgage refinance that includes repairs.
Example 1: You buy a property that needs substantial repairs and include eligible renovation costs in the financing.
Example 2: You investigate refinancing an existing mortgage while funding qualifying improvements.
Quick Tip: Ask an FHA-approved mortgage lender to explain current credit, property, contractor, and renovation requirements. Compare the total mortgage costs before refinancing solely to fund improvements.
5. Home Equity Loans
Meaning: A home equity loan allows eligible homeowners to borrow against the equity they have built in their property. It typically provides a lump sum with scheduled repayments.
Best for: Homeowners with sufficient equity, stable income, and a realistic repayment plan.
Example 1: You explore a home equity loan to fund a major kitchen renovation.
Example 2: You compare equity financing for replacing several aging windows and repairing exterior damage.
Quick Tip: A low credit score may make approval more difficult or increase your rate. Because your home secures the debt, missed payments can lead to foreclosure.
6. Home Equity Lines of Credit (HELOCs)
Meaning: A HELOC is a revolving credit line secured by your home’s equity. You can generally draw funds as needed during the borrowing period, subject to the lender’s terms.
Best for: Homeowners with qualifying equity who expect renovation expenses to occur in stages.
Example 1: You draw funds in stages as a contractor completes different parts of a bathroom renovation.
Example 2: You use a credit line for approved repairs that arise during a larger remodeling project.
Quick Tip: Many HELOCs have variable interest rates, so payments can rise. Review the draw period, repayment period, fees, and foreclosure risk before borrowing.
7. USDA Section 504 Home Repair Loans and Grants
Meaning: The USDA Section 504 program helps eligible very-low-income homeowners in qualifying rural areas repair, improve, or modernize their homes. Eligible homeowners aged 62 or older may also qualify for grants to remove health and safety hazards.
Rural Development+1
Best for: Income-qualified rural homeowners who cannot obtain affordable credit elsewhere.
Example 1: An eligible homeowner seeks help repairing a roof that allows water into the house.
Example 2: An older homeowner explores grant assistance to remove a serious safety hazard.
Quick Tip: The USDA lists loans of up to $40,000 at a fixed 1% interest rate for up to 20 years, and grants of up to $10,000 for eligible applicants. These are program limits, not guaranteed awards. Check current eligibility and availability through the official USDA program page.
Rural Development+1
8. Local Home Repair Grants and Assistance
Meaning: Some state and local governments, housing agencies, and nonprofit organizations provide financial help for essential home repairs. Programs may target low-income households, older adults, people with disabilities, or homes with health and safety problems.
Best for: Homeowners who meet local income, property, or household requirements.
Example 1: You apply for a city program that helps eligible residents repair unsafe electrical systems.
Example 2: You contact a local housing agency about assistance with accessibility improvements.
Quick Tip: Contact your city or county housing department and ask about emergency repair grants, rehabilitation programs, and weatherization assistance. Confirm whether the funds are grants or loans, because some programs require repayment under certain conditions.
9. Credit Union Home Improvement Loans
Meaning: Credit unions offer personal loans and other financing products to eligible members. Their underwriting rules, rates, and membership requirements vary.
Best for: Borrowers who want to compare a local or community-based lender with online loan offers.
Example 1: You ask a credit union about financing a necessary roof repair.
Example 2: You compare its fixed-rate renovation loan with offers from online lenders.
Quick Tip: Ask whether the credit union considers your full financial situation rather than relying on your credit score alone. Membership does not guarantee approval or a low rate.
10. Contractor Financing
Meaning: Some home improvement contractors partner with financing companies or offer payment plans through third-party lenders. These arrangements may spread the cost of an approved project over time.
Best for: Homeowners who want to compare project financing while obtaining contractor estimates.
Example 1: You review a financing offer while arranging the replacement of a damaged furnace.
Example 2: You compare payment plans for installing energy-efficient windows.
Quick Tip: Get the financing terms in writing and compare the offer with independent loans. Watch for deferred-interest promotions, high APRs after promotional periods, and pressure to sign before reviewing the contract.
Comparison Table: Home Improvement Financing Options
| Alternative | Best Used In | Tone / Main Consideration |
|---|---|---|
| Personal loan | Small to medium projects | Predictable, usually unsecured |
| Secured personal loan | Borrowers with eligible collateral | May offer better terms, but collateral is at risk |
| FHA Title I loan | Eligible property improvements | Government-insured through approved lenders |
| FHA 203(k) loan | Home purchase or qualifying refinance with renovations | Mortgage-based, with additional requirements |
| Home equity loan | Large projects with sufficient equity | Fixed lump sum, home at risk |
| HELOC | Renovations completed in stages | Flexible borrowing, often variable-rate |
| USDA Section 504 | Eligible rural homeowners | Low-cost assistance for qualifying applicants |
| Local repair grants | Eligible households with essential repair needs | May reduce or eliminate borrowing |
| Credit union loan | Members comparing local lending options | Terms depend on the institution |
| Contractor financing | Contractor-managed renovation projects | Convenience varies; compare total cost |
Common Mistakes to Avoid
1. Applying to Too Many Lenders at Once
Submitting multiple formal applications in a short period may lead to several hard credit inquiries. Compare lenders first and use soft-credit prequalification when available.
2. Focusing Only on the Monthly Payment
A lower monthly payment may come with a longer repayment term and higher total interest. Compare the APR, fees, repayment period, and total amount you will repay.
3. Ignoring the Risk of Secured Loans
A secured loan may seem easier to obtain, but missing payments can put your collateral at risk. If you use your home as security, default could ultimately lead to foreclosure.
4. Assuming Government Programs Guarantee Approval
Federal programs have specific eligibility rules. An FHA-insured loan still requires lender approval, and USDA assistance has income, location, and other requirements. Verify eligibility before planning your renovation around expected funding.
HUD+2
5. Accepting a Loan Without Reading the Contract
Do not sign until you understand the interest rate, fees, payment schedule, late charges, and consequences of missed payments. Be especially cautious if a contractor pressures you to sign financing paperwork immediately.
Frequently Asked Questions
1. Can I get home improvement loans with bad credit?
Yes, some lenders offer home improvement financing to borrowers with poor or limited credit histories. Approval depends on the lender’s criteria, income, existing debts, payment history, and other factors. You may face higher rates or fees, so compare prequalified offers and investigate assistance programs before choosing a loan.
2. What credit score do I need for a home improvement loan?
There is no universal minimum credit score for home improvement loans. Some lenders accept lower scores, while others require stronger credit. A score below 580 can limit your options, but it does not automatically mean you will be rejected. Check each lender’s current requirements and consider your overall financial situation.
3. Can I get a home repair loan with a 500 credit score?
It may be possible, but options can be limited. Some lenders consider applicants with very low scores, while others may decline the application or offer expensive terms. Check whether you qualify for local repair assistance, USDA Section 504 support, or other suitable programs before accepting a high-cost loan.
4. Are there government grants for home repairs with bad credit?
Some government programs provide repair assistance to eligible homeowners, and credit score requirements vary by program. For example, the USDA Section 504 program offers loans to qualifying rural homeowners and grants to eligible homeowners aged 62 or older for health and safety hazards. Income, location, and other eligibility conditions apply.
Rural Development+1
5. Can I get a home improvement loan without home equity?
Yes. An unsecured personal loan may be available without home equity because it does not use your home as collateral. However, lenders still review your credit, income, debts, and ability to repay. If you cannot qualify affordably, explore credit unions, nonprofit assistance, local repair programs, and ways to reduce the project cost.
6. Is a home improvement loan better than a credit card?
It depends on the interest rate, fees, repayment period, and amount you need. A fixed-rate personal loan can provide predictable payments, while a credit card may offer flexibility or a promotional rate. Compare the full cost and understand when any introductory rate expires before choosing either option.
7. How can I improve my chances of approval with bad credit?
Review your credit reports for errors, pay bills on time, and reduce existing debt where possible. Request estimates from contractors so you borrow only what you need. You can also compare lenders that offer soft-credit prequalification or ask whether a qualified co-borrower could help, while understanding that both applicants may be responsible for repayment.
8. What should I do if I cannot qualify for a home improvement loan?
Start by separating urgent safety repairs from cosmetic upgrades. Ask your local housing department, community action agency, or nonprofit organizations about repair assistance. You could also seek multiple contractor estimates, complete safe and manageable work in stages, or save toward nonessential improvements. Avoid payday loans and other high-cost financing that could make your financial situation worse.
Conclusion
Finding home improvement loans with bad credit takes careful comparison, but a low credit score does not automatically close every door. Personal loans, credit union financing, secured loans, and government-backed programs may provide ways to pay for necessary repairs. The best option depends on your income, credit history, available equity, project costs, and ability to make regular payments.
Start by getting written estimates for your repairs and checking whether you qualify for grants or local assistance. Then compare several financing offers using their APRs, fees, repayment terms, and total costs. Avoid borrowing more than you need, and think carefully before using your home as collateral.
The most important takeaway: Choose financing that solves your home repair problem without creating a bigger financial burden. If a loan payment would stretch your budget too far, explore assistance programs or delay nonessential improvements until you can afford them.